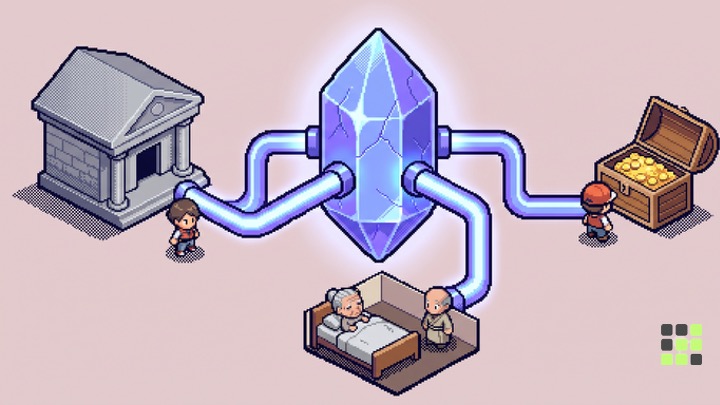
California's 5% Wealth Tax vs an 80% Founder Pledge
I compare California's wealth tax to AI founders' pledges, then flag how to read investment, tax, and jobs data before drawing conclusions.
BusinessWhat I check first when I hear investment totals went up
According to an August announcement from Korea’s Ministry of SMEs and Startups, domestic venture investment in the first half of this year totaled ₩8.8676 trillion (~$6.6 billion). That’s up 54.3% from the same period last year — the second-highest first-half figure on record.
In the US, a handful of AI companies raised far larger sums. OpenAI’s round, announced in March, was $122 billion. Anthropic announced $30 billion in February and $65 billion in May. Add up all three rounds across both companies and you get $217 billion. These figures include committed capital, so they don’t mean that much has already been spent on hardware or hiring.
When I see numbers like these, the first thing I check is which deals inflated the total. Even if aggregate investment rises, it might mean only a handful of companies found it easier to raise money.
PitchBook and the National Venture Capital Association’s (NVCA) Q1 2026 report illustrates this well. US venture investment set a quarterly record, but strip out the five largest deals and the total drops by 73.2%. In other words, you need to separate what large AI companies are raising from the funding conditions everyone else is facing.
When those companies’ valuations rise, so do the paper fortunes of founders and employees. State governments start counting on tax revenue, and founders pledge donations. This is where I check one more layer. How much a company raised, what its stock is valued at, and actual taxes or donations paid are three different numbers. Fail to separate them, and unspent assets start to read as money already circulating through the local economy.
Higher Valuations Don’t Mean Immediate Tax Revenue
California is a state whose tax revenue is heavily influenced by high earners’ income and capital gains. Capital gains refer to the profit made from selling assets like stock. An announcement that a company’s valuation has risen is a completely different moment in time from a shareholder actually selling stock for a profit.
A 2017 study by California’s Legislative Analyst’s Office (LAO) examined this fiscal structure. Applying the tax code of that era to income data from 1990–2014, the analysis estimated that the volatility of personal income tax revenue was about five times greater than the volatility of residents’ overall personal income. This isn’t a direct measurement of how current tax revenue swings, but it does show how much stock prices and high earners’ income can shake state finances.
Stock-based compensation is taxed at different times depending on the type of award and the conditions attached to vesting or selling. You can’t calculate how much a state government will collect just by looking at an investment announcement. You need to know who actually holds the stock and when the taxable income is realized.
What worries me here is the sustainability of spending. When revenue rises during a boom, it creates room to launch new initiatives. But those initiatives need to keep running the following year too, even as asset prices — and the tax revenue tied to them — may fall. You have to judge how much of your recurring annual spending a temporary revenue bump can actually cover.
The possibility of AI companies going public in the future should be read the same way. The outcome depends on whether the IPO actually happens, when shareholders are able to sell, and at what price the shares trade. Projected tax revenue is a forecast built on these conditions — it is not a budget you’ve already secured.
An 80% pledge and actual disbursements are two different things
Anthropic’s Dario Amodei wrote in an essay this January that all of the company’s co-founders had pledged to donate 80% of their wealth. He explained that employees had also pledged to donate company stock, with the company matching those contributions. In the same piece, he wrote that alongside private efforts, government intervention and well-designed progressive taxation would also be needed.
When most of someone’s wealth is held in equity, the pledge’s assessed value grows as the company’s valuation rises. But a promise to “donate 80% of my wealth” tells you nothing about how much money goes to which organization this year. You have to check three things separately: the pledged percentage, the current valuation of the assets, and the amount actually disbursed.
The OpenAI Foundation needs the same kind of distinction drawn. When the company announced its capital restructuring in October 2025, the foundation’s equity stake was valued at roughly $130 billion. That’s a valuation at a point in time. It doesn’t mean the foundation holds that much cash on hand, ready to spend on programs immediately. You also have to be careful about calculating “current funds available for giving” by multiplying a new company valuation by an old equity percentage, without confirming how the stake itself may have shifted following subsequent funding rounds.
The timing of when money actually gets spent also depends on the mechanism of giving. A donor-advised fund (DAF) is a vehicle where you donate assets upfront and later recommend which organizations should receive support. According to the U.S. Internal Revenue Service, legal control of the donated assets transfers to the public charity that administers the fund. The donor retains advisory privileges — recommending grantees, for instance — but this is different from a structure where the donor keeps ownership of the money in their own account.
That means the date assets are transferred into a fund and the date they’re actually spent on programs in the field need to be treated as separate events. The size of a giving pledge matters, but it doesn’t tell you when or what kind of help reaches the people who need it.
I think the criteria used to decide where the money goes also need to be made public. If programs whose impact is easy to measure get prioritized, needs that resist quantification can end up pushed to the back of the line. Conversely, if large sums go toward research where near-term results are hard to judge — long-term AI risk, for example — then the assumptions behind that funding and the standards for evaluating its results need to be spelled out. Goodwill in giving and scrutiny of how funds get allocated aren’t mutually exclusive — they can, and should, go hand in hand.
A 5% wealth tax and an 80% giving pledge aren’t comparable just by their percentages
California’s November 3rd ballot includes Proposition 40. According to the Legislative Analyst’s Office, it would impose a one-time tax on California residents whose net worth exceeds $1 billion as of year-end, effective January 1, 2026. Real estate and pension/retirement accounts carry exemptions. The 5% tax would be payable starting in 2027, and the design allocates 90% of the resulting revenue to healthcare.
The Legislative Analyst’s Office estimates this could generate tens of billions of dollars in additional revenue over multiple years. At the same time, it projects that personal income tax revenue could decline annually as some taxpayers relocate elsewhere. That annual decline is estimated at under $1 billion. This is a proposal that requires weighing a one-time inflow against a recurring, ongoing loss.
Placed side by side, 5% and 80% make the philanthropic pledge look like the far heavier commitment. But the people involved, the scope of assets being calculated, and the timing of execution aren’t the same in each case. Nor does a voluntary giving pledge substitute for a legally mandated tax obligation.
The distinction I find more important is who decides how the money gets used, and through what process. Taxes are spent according to law and budgetary procedure. Donations are allocated according to the purposes and decisions of foundations or public-interest organizations, and depending on the arrangement, the donor’s own preferences may shape that allocation. Both can serve the public good, but they don’t operate through the same decision-making structure.
It’s hard to argue that a donor pledging a large percentage has thereby substituted for the role of public finance. Conversely, the mere fact that something is a tax doesn’t mean every dollar of spending is effective. I think what matters is not just the amount, but also the timing of execution, who benefits, and whether the decision-making process and its outcomes are made public.
If local employment rose, we need to ask what kind of jobs actually grew
Attracting investment doesn’t translate directly into local employment either. A California company can raise money and then build a data center in another state. Where a company is headquartered and where its money gets spent can be two different places.
The Economic Innovation Group (EIG) analyzed California employment from March 2022 to March 2026 using Bureau of Labor Statistics data. Over this period, healthcare and social assistance employment grew 25.3%, while total employment grew 3.4%. Employment across all other industries combined actually fell 0.3%.
This is why it’s hard to explain local job growth purely through big AI companies attracting investment. EIG suggests that expanded healthcare coverage and public assistance programs may have driven up service usage and employment. But not all demand for healthcare and caregiving comes from government budgets. We need to look at public insurance, private insurance, and household spending together.
It’s also worth checking why employment statistics shifted in the first place. In an April 2026 analysis, the Center for New York City Affairs, a New York City policy research center, flagged something odd: roughly 43,000 home health aide jobs in New York City appeared to vanish overnight in April 2025. Around the same time, a similar-sized number of jobs appeared elsewhere in New York State, and there was no corresponding drop in employment statistics for city residents themselves.
The researchers interpreted this as the result of reclassification tied to consolidation among the intermediary firms that process home care benefit payments, along with changes in how reporting was done—not evidence of mass layoffs or workers actually relocating. It’s a cautionary example: a sudden shift in headcount numbers doesn’t necessarily mean customers disappeared or a new market emerged.
Oswarld’s Lens
When building GTM strategy, there were two scenarios I was always wary of.
The first is when two big deals fill out a quarter’s pipeline. Even if you beat your target that quarter, you need to separately check whether the process of landing those deals produced a customer acquisition channel you can use repeatedly. There’s no guarantee a big deal repeats itself next quarter. So I always looked at the total figure alongside what remained after stripping out the top two deals.
This isn’t about discounting the value of landing a big contract. I just think winning a great deal and building a repeatable method for acquiring customers are two different things that deserve separate evaluation. I apply the same standard when looking at total venture capital figures — I check what terms companies are raising money on once you exclude the mega-deals.
The second habit I was wary of was estimating market size using industry employment figures — especially for B2B products. The logic goes: calculate market size based on how many people work in the target job function and how fast that number is growing. But an increase in the number of people who’d use your product is not the same as an increase in the budget available to buy it.
Take a product built for home care workers as an example. You first need to figure out who actually pays. Whether it’s the individual worker, the employer, or an insurance/public-program budget determines who you sell to and what the purchasing process looks like. Even if the need is significant, if the institution has no discretionary budget, it’s hard to convert that into a contract. Conversely, in a market with a stable funding source, understanding the budget execution process can become the crux of your GTM strategy.
Reading through this round of materials reconfirmed for me how to avoid the mistake of inflating numbers. For investment totals, look at how much weight big deals carry. For assets and donations, look at the actual amount that can be spent and when. For employment, look at which job categories are growing and what purchasing budgets exist.
I trust a business plan that explains which customers can buy our product with what budget far more than one that simply claims the market has grown. That’s exactly why I looked at the pipeline minus the top deals, and why I checked who actually pays right after looking at worker headcounts.
💬 Have you ever changed your judgment on market size after checking the actual purchasing budget behind it?
Keep the perspective, not the noise.
We choose one consequential shift and trace what sits beneath it, every other day.
Confirm once to finish subscribing.
Already a subscriber? Sign in to join the conversation


References
- Korea Ministry of SMEs and Startups, 2026 First-Half Venture Investment Tally
- OpenAI, March 2026 Funding Announcement
- Anthropic, Series G Funding·Series H Funding
- PitchBook·NVCA, Q1 2026 Venture Monitor
- California LAO, Study on Income Tax Structure Volatility·Analysis of 2026 Proposition 40
- Dario Amodei, The Adolescence of Technology
- OpenAI, October 2025 Capital Restructuring and Foundation Equity Stake
- US Internal Revenue Service, Donor-Advised Funds
- EIG, Analysis of California’s Healthcare and Care Employment
- Center for New York City Affairs, Analysis of Home Health Aide Job Reclassification
Related issues
Don't Cram Discovery, Understanding, and Conversion Into One Video
A single short-form clip can't introduce a brand, explain it, and close the sale—each channel needs its own job.
BusinessSet Data, Approval, and Recovery Rules Before Adopting AI
Public-sector guidelines and Korea's AI Basic Act reveal why assigning data, approval, and recovery duties matters more than picking a model.
BusinessWhen Solving Hard Problems No Longer Proves Expertise
25 Fields Medalists and 31% of the consulting market are pointing to the same breakdown.
Business
Your take shapes the next issue
What resonated most in this issue, or where has your experience been different?